Creuto is now an OpenAI Select Partner Read More

Banking & Financial Services · Specialisation

Lending Software Development Services

Faster Loan Decisions With Less Manual Work.

We build loan origination, credit decisioning, servicing, and collections platforms for banks, NBFCs, and digital lenders, automating paperwork and approvals while keeping lending decisions explainable and compliant.

  • AML, KYC and fair lending controls built in
  • Experian, Equifax, TransUnion and open banking data
  • Senior lending engineering team

Plan your lending platforms project

Tell us what you want to build. A senior engineer, not a sales script, replies within one business day.

What's your budget range?

Your idea is protected. NDA available on request.

Trusted by teams building what's next

  • Creuto client 1
  • Creuto client 2
  • Creuto client 3
  • Creuto client 4
  • Creuto client 5
  • Creuto client 6
  • Creuto client 7
  • Creuto client 8
  • Creuto client 9
  • Creuto client 10
  • Creuto client 11
  • Creuto client 12
  • Creuto client 13
  • Creuto client 14
OVERVIEW

Software shaped around how lending platforms really works.

Borrowers expect a lending decision in minutes, yet many lenders still rely on emailed documents, manual data entry and underwriting spread across spreadsheets, a loan system and a credit bureau portal. The result is slow approvals, inconsistent decisions, high cost per loan and applicants who accept a faster offer elsewhere before your team has finished reviewing their file.

As a lending software development company, we build platforms that cover the full loan lifecycle: application, identity and income verification, credit decisioning, offer, e-signature, disbursement, servicing and collections. Each stage is connected to credit bureaus such as Experian, Equifax and TransUnion, open banking data through Plaid or account aggregators, and your core or loan ledger.

Decisions stay explainable and auditable. Rules engines and scoring models record every input, version and outcome, so adverse action reasons, fair lending reviews and regulator questions can be answered. AML and KYC checks, affordability assessments, consumer credit rules, GDPR and local requirements such as RBI digital lending directions in India are designed into the workflow rather than added afterwards.

Whether you lend to consumers, SMEs or merchants, through your own channels or embedded in a partner's checkout, we build lending software that approves good borrowers faster, prices risk consistently and keeps portfolios healthy. Configurable products let your team launch new loan types, rates and terms without another development project.
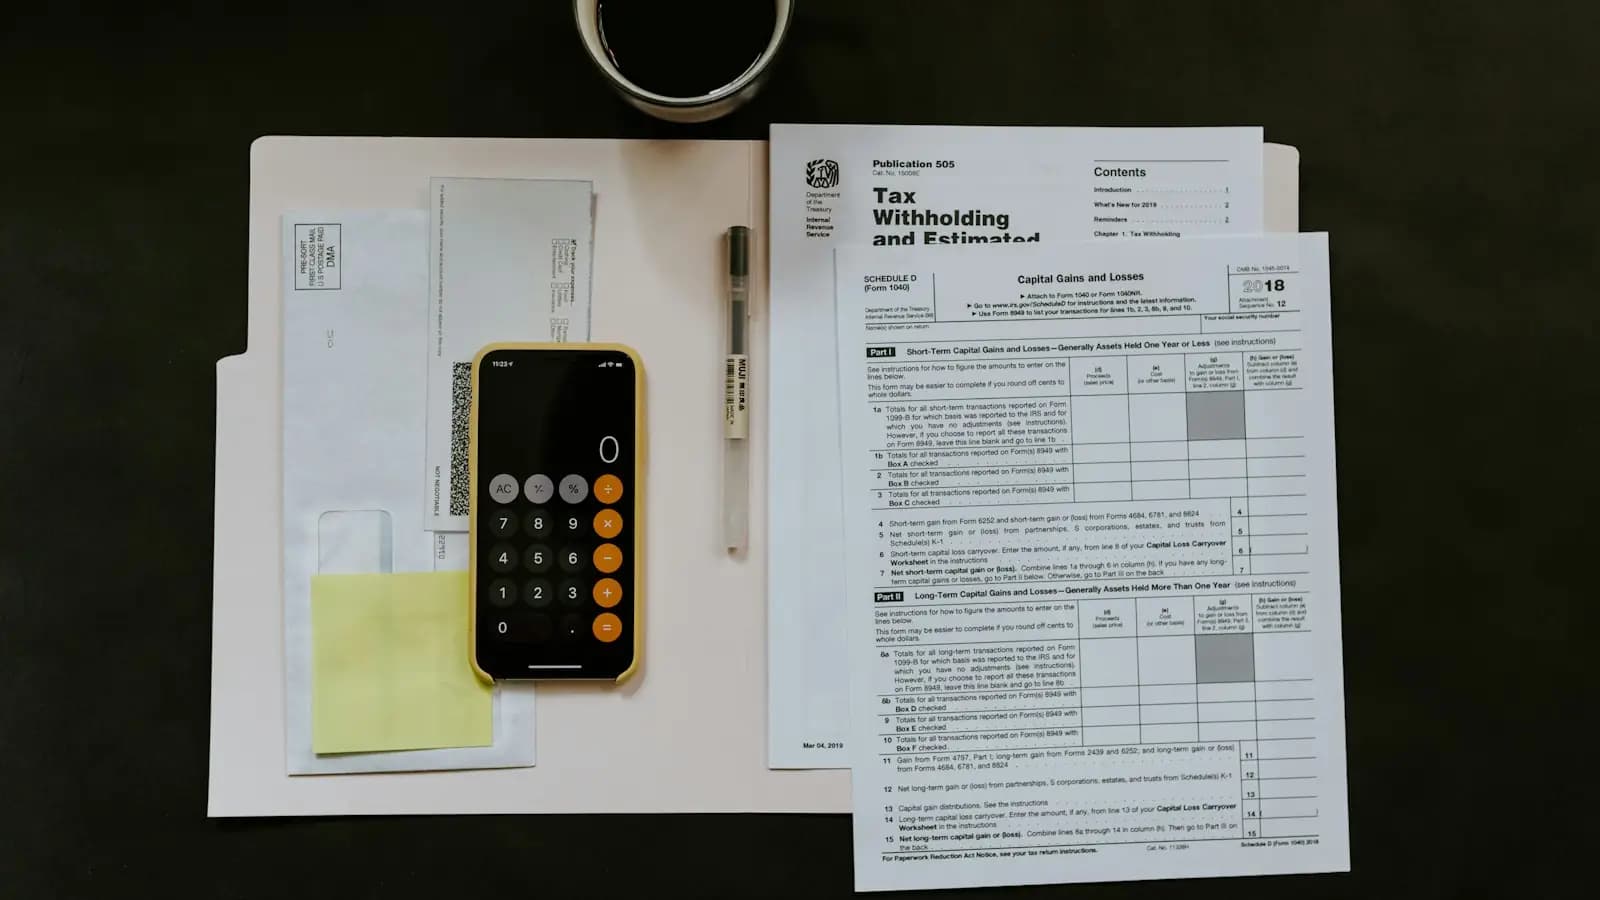
Why lending platforms teams build with Creuto

Digital loan origination

Mobile and web applications with pre-filled data, document upload, bank statement connection and e-signature, designed so applicants finish in one sitting on any device.

Explainable credit decisioning

Configurable rules and scoring models fed by bureau, open banking and alternative data, with every decision versioned, reasoned and ready for audit or adverse action notices.

Automated verification

Identity, income and bank statement checks through Onfido, Plaid and account aggregators, plus AI document extraction that removes manual keying from underwriting.

Flexible loan servicing

Amortisation schedules, interest accrual, fees, restructures, top-ups and early settlement, posted to a double-entry ledger that reconciles with your finance system.

Compliant collections

Segmented reminders, payment plans, promise-to-pay tracking and agent workflows that follow contact rules and treat customers in financial difficulty fairly.

Embedded and point-of-sale lending

BNPL and instalment products integrated into merchant checkouts and partner apps, with instant decisions and merchant settlement handled by the platform.

0+

Products delivered

0+

Years of engineering

0%

Client satisfaction

0+

Industries served

0+

Countries with live products

WHAT WE BUILD

Lending Platforms software solutions we build.

Each one designed with your teams, integrated with the systems you already run, and engineered to scale.

RELATED AREAS

More Banking & Financial Services software we build

Other banking & financial services areas with a dedicated page.

TYPES OF SOLUTIONS

Types of lending platforms apps and software we develop.

The product categories lending platforms organisations most often ask us to build, from focused mobile apps to multi-tenant platforms.

  1. 01

    Loan origination systems

    Applications, verification, underwriting and approval workflows for retail and SME lending.

  2. 02

    Loan management and servicing software

    Schedules, accruals, repayments, statements and restructures on an auditable ledger.

  3. 03

    Credit decisioning engines

    Rules and model execution with bureau and open banking data, versioning and decision explanations.

  4. 04

    Buy now pay later apps

    Point-of-sale instalments with instant approval, merchant integration and repayment management.

  5. 05

    Digital personal loan apps

    Mobile-first consumer lending with eKYC, instant decisions and same-day disbursement.

  6. 06

    SME and invoice finance platforms

    Business lending, invoice discounting and revenue-based finance with accounting software connections.

  7. 07

    Mortgage origination platforms

    Application, affordability, valuation, conveyancing and offer workflows for brokers and lenders.

  8. 08

    P2P and marketplace lending platforms

    Borrower and investor portals with loan listing, funding, servicing and investor reporting.

  9. 09

    Debt collection and recovery software

    Segmentation, contact strategies, payment plans and agency management for arrears.

KEY FEATURES

Must-have features of a lending platforms platform we build in.

Grouped by who uses them. Every feature below is one we have shipped to production, not a wishlist.

/01

Borrower app

From application to final repayment.

  • Eligibility check without credit impact
  • Guided application with pre-filled data
  • eKYC and document upload
  • Bank statement connection via open banking
  • Instant offer and e-signature
  • Repayment schedule and balance view
  • Early repayment and top-up requests
  • Payment plans and hardship support
/02

Underwriting and collections tools

For credit, operations and collections teams.

  • Underwriting workbench with full file
  • Bureau and banking data summaries
  • Referral queues and manual overrides
  • Fraud and identity alerts
  • Disbursement approvals with maker-checker
  • Collections queues by arrears stage
  • Promise-to-pay and contact history
  • Agency and legal referral tracking
/03

Admin and risk console

Configure products and watch the portfolio.

  • Loan product, rate and fee configuration
  • Decision rules and scorecard versions
  • Champion and challenger testing
  • Portfolio, vintage and delinquency analytics
  • Partner and merchant configuration
  • Ledger and general ledger exports
  • Regulatory and bureau reporting
  • Audit logs and access reports
CHALLENGES WE SOLVE

What holds lending platforms teams back.

The problems we most often help lending platforms organisations solve, and design every engagement around.

  1. 01

    Manual underwriting

    Document review, data entry and checks across several systems slow decisions, raise cost per loan and lose applicants to faster competitors.

  2. 02

    Credit risk and data quality

    Lenders need reliable bureau, banking and alternative data and consistent rules, or approval quality varies by underwriter and portfolios deteriorate.

  3. 03

    Explainability and fair lending

    Regulators expect lenders to explain each decision and show that models do not discriminate, which spreadsheets and opaque scores cannot evidence.

  4. 04

    Collections efficiency

    Late payments need timely, segmented and compliant follow-up, but manual chasing is costly and inconsistent across agents.

  5. 05

    Inflexible legacy loan systems

    Launching a new product, rate structure or partner channel on an older loan system often means months of change requests.

SELECTED WORK

Products we have shipped. Results we can point to.

Real products designed and engineered by Creuto end to end, with the operational depth banking & financial services and lending platforms projects demand.

Enterprise HR & Payroll Platform – Nomina
/01 · HR & Payroll

Enterprise HR & Payroll Platform – Nomina

A complete, end-to-end HR and payroll platform covering employee onboarding to exit, attendance, leave, payroll processing, compliance, and reporting — built and delivered by Creuto from scratch.

5×

Faster Payroll Processing

20 wk

Time to Market

5

User Roles

View Case Study
AI-Powered CRM & Sales Engagement Platform
/02 · Sales / CRM

AI-Powered CRM & Sales Engagement Platform

A complete Before-Sales and After-Sales CRM platform — AI-powered market insights, Kanban pipeline management, complaint tracking, and role-based dashboards built and delivered by Creuto end to end.

2

CRM Modules (Before & After)

AI

Market Intelligence Engine

360°

Customer Lifecycle Coverage

View Case Study
Custom Cloud ERP for Large-Scale Industrial Operations
/03 · Enterprise ERP

Custom Cloud ERP for Large-Scale Industrial Operations

A fully custom, browser-based ERP system built to unify every department, eliminate silos, and scale with the business — designed and delivered by Creuto end to end.

4

Departments Unified

1

Source of Truth

100%

Browser-Based Access

View Case Study
COMPLIANCE AND SECURITY

Compliance and security, designed in.

The lending platforms standards we build against and the controls behind them. Your compliance team keeps ownership; we make the software easy to certify.

Lending regulations we build for

  • AML, KYC and CFT obligations
  • Consumer credit rules including FCA Consumer Duty (UK)
  • Fair lending and adverse action requirements (US)
  • RBI digital lending directions (India)
  • SAMA finance company rules (Saudi Arabia)
  • CBUAE consumer protection standards (UAE)
  • GDPR and UK GDPR

Credit data and decisioning standards

  • Credit bureau reporting formats by market
  • Open banking consent and data scopes
  • India Account Aggregator framework
  • Model risk management and validation
  • Affordability and creditworthiness assessments
  • Decision explainability and reason codes

Security controls

  • Encryption of personal and financial data
  • Role-based access with maker-checker
  • Tamper-evident decision and audit logs
  • Secure document storage and retention
  • Multi-factor authentication for staff
  • Penetration testing before launch

Platform quality

  • SOC 2 and ISO/IEC 27001 aligned controls
  • Ledger reconciliation checks
  • Interest and fee calculation testing
  • Load testing for campaign peaks
  • Disaster recovery with tested failover
  • Accessibility to WCAG 2.2 AA
INTEGRATIONS

Lending Platforms integrations we connect.

The platforms, standards and third-party services a product in this sector usually has to talk to. If yours is not listed, it is almost certainly something we have connected before.

/01Credit bureaus and data

  • Experian
  • Equifax
  • TransUnion
  • CIBIL
  • SIMAH
  • Al Etihad Credit Bureau

/02Banking and open banking data

  • Plaid
  • TrueLayer
  • Account Aggregators (India)
  • Temenos
  • Mambu
  • Finastra

/03Identity, documents and signatures

  • Onfido
  • Sumsub
  • Jumio
  • DocuSign
  • Ocrolus
  • Aadhaar eKYC via licensed providers

/04Payments and communication

  • Stripe
  • Razorpay
  • GoCardless
  • Network International
  • Twilio
  • Salesforce Financial Services Cloud
WHY CREUTO

Why choose Creuto as your lending platforms software development company

The reasons clients in this sector give when they recommend us, not the ones we would pick ourselves.

Either we build it exceptional, or we don't.

The standard every lending platforms product leaves our studio with.

0+

Products delivered

0+

Years of engineering

0%

Client satisfaction

Start a conversation
  1. /01

    We speak credit risk

    Discovery covers scorecards, policy rules, vintages and arrears, so the platform matches how your risk team thinks.

  2. /02

    Every decision explainable

    Inputs, rule versions and reasons are stored for each decision, ready for customers, auditors and regulators.

  3. /03

    Configurable, not hard-coded

    Products, rates, rules and workflows change through configuration, so your team launches without another project.

  4. /04

    Accurate money movement

    Accruals, fees and repayments post to a reconciled ledger, tested against your own calculations.

  5. /05

    Partner with your risk team

    We stay on after launch to support policy changes, new data sources and model updates.

BENEFITS

Benefits of custom lending platforms software over off-the-shelf tools.

What organisations in this sector gain when the software is built around their workflows rather than the other way around.

  1. 01

    Faster time to decision

    Automated verification and decisioning move good applicants from application to offer in minutes.

  2. 02

    Lower cost per loan

    Straight-through processing removes manual keying and reduces underwriter time on clear-cut cases.

  3. 03

    More consistent credit quality

    Rules and models apply policy the same way every time, reducing variance between underwriters.

  4. 04

    Better collections outcomes

    Segmented, timely contact and self-service payment plans recover more while treating customers fairly.

  5. 05

    New distribution channels

    APIs and embedded journeys let you lend through merchants, platforms and partners.

  6. 06

    Audit-ready lending

    Decision logs, document trails and reports make regulatory reviews and investor due diligence simpler.

HOW WE WORK

Our lending platforms software development process.

Transparent, sprint-based and built around decisions you can see. You know what ships, when, and why at every step.

Start Your Project
  1. 01

    Credit and product discovery

    We map your loan products, borrower segments, credit policy, data sources and regulators, and the measures that matter, such as time to decision and cost per loan.

  2. 02

    Architecture and compliance plan

    Decision engine design, ledger model, bureau and banking integrations, data retention and the controls your licence requires are documented before design.

  3. 03

    Journey design and validation

    Application and servicing journeys are tested with real borrowers and underwriters, including referrals, declines, missed payments and hardship cases.

  4. 04

    Agile engineering

    Two-week sprints with credit risk and compliance reviewing working software, built against bureau and open banking sandboxes from the start.

  5. 05

    Integration, QA and hardening

    Interest and fee calculation tests, decision regression packs, reconciliation checks, load tests and a penetration test before go-live.

  6. 06

    Controlled launch and growth

    Launch with a limited product or cohort, monitor approval, default and fraud data, then tune rules and expand products and channels.

TECHNOLOGY STACK

Technology stack for lending platforms software development.

Chosen per project for longevity, hiring depth and fit with your existing systems, never by fashion.

/01Mobile

  • Swift
  • Kotlin
  • Flutter
  • React Native

/02Web and backend

  • React
  • Next.js
  • TypeScript
  • Node.js
  • Java
  • Spring Boot
  • Python
  • FastAPI

/03Decisioning and ledgers

  • Rules engines
  • Temporal
  • Kafka
  • Double-entry ledger
  • REST
  • Webhooks

/04Data

  • PostgreSQL
  • Redis
  • Snowflake
  • BigQuery
  • ClickHouse

/05Cloud and DevOps

  • AWS
  • Azure
  • Google Cloud
  • Docker
  • Kubernetes
  • Terraform
  • GitHub Actions

/06AI and credit models

  • Scikit-learn
  • PyTorch
  • Claude
  • OpenAI
  • LangChain

/07Security and identity

  • OAuth 2.0
  • OpenID Connect
  • Keycloak
  • AWS KMS
  • Vault

AI IN LENDING PLATFORMS

AI that reads the file, and explains the decision.

We apply AI in lending where it removes manual underwriting work and sharpens risk assessment, with every model documented, monitored for bias and drift, and overseen by your credit team.

Explore our AI engineering
  • Bank statement and payslip extraction
  • Cash flow based affordability analysis
  • Credit risk scoring with reason codes
  • Application fraud detection
  • Collections prioritisation and contact timing
  • Underwriter assistants that summarise files
TRENDS

Trends shaping lending platforms software right now.

The shifts we design for so a product launched this year is still the right product in three.

  1. 01

    Open banking and cash flow underwriting

    Lenders are using bank transaction data alongside bureau scores to assess affordability and lend to thin-file borrowers.

  2. 02

    Regulation of BNPL and digital lending

    Regulators in the UK, India and elsewhere are bringing BNPL and app-based lending under clearer consumer credit rules.

  3. 03

    AI in underwriting with explainability

    Machine learning and document AI speed up underwriting, while regulators expect explanations, bias testing and model governance.

  4. 04

    Embedded lending

    Credit is moving into checkouts, marketplaces and B2B platforms, so lenders need APIs and instant decisions.

  5. 05

    Consumer Duty and fair outcomes

    UK Consumer Duty and similar rules push lenders to evidence good outcomes, including for customers in financial difficulty.

COST AND TIMELINE

How much does lending platforms software development cost?

There is no honest single number. Scope, integrations and compliance drive the budget, so we price against a written scope after discovery. The factors below are what move it.

  1. 01

    Lifecycle stages in scope

    Origination alone is smaller than origination, servicing and collections on one platform.

  2. 02

    Number of loan products

    Each product type brings its own schedules, fees, rules and documents.

  3. 03

    Data and bureau integrations

    Every bureau, open banking provider and verification service adds integration and testing.

  4. 04

    Decisioning sophistication

    Simple policy rules cost less than scorecards, champion and challenger testing and machine learning models.

  5. 05

    Ledger and accounting requirements

    Accruals, provisioning and general ledger integration add calculation and reconciliation work.

  6. 06

    Migration of existing loans

    Moving live loans with balances and history requires careful mapping and reconciliation.

EngagementTypical scopeTimeline
Validation MVPOne loan product, digital application, bureau check, rules-based decisioning and disbursement.10 to 14 weeks
Production lending platformOrigination, decisioning, servicing and collections, borrower app, underwriting tools, ledger and reporting.4 to 7 months
Enterprise or multi-product lenderMultiple products and channels, embedded lending APIs, loan migration, ML models and portfolio analytics.8 to 14 months, phased
BUSINESS MODELS

How lending platforms products make money.

Revenue models we have built billing, reporting and growth loops for. Most products combine two or three.

  1. 01

    Interest income

    Margin between the borrower rate and cost of funds, priced by risk.

  2. 02

    Origination and servicing fees

    Arrangement, late payment and early settlement fees where regulation permits.

  3. 03

    Merchant fees for BNPL

    Merchants pay a discount rate in exchange for higher conversion and basket size.

  4. 04

    Lending-as-a-service licences

    Banks and platforms license the lending stack with implementation and support fees.

  5. 05

    Marketplace and investor fees

    P2P platforms charge borrowers and investors for listing, servicing and collections.

HOW WE DELIVER

Services behind our lending platforms work

The engineering disciplines every project in this sector draws on. Each has its own page with process, stack and FAQs.

TESTIMONIALS

Don't take our word for it.

Founders and product leaders on what it is like to build with Creuto.

“We always felt supported and in sync with their team.”

Creuto's work streamlined the client's processes, improved batch traceability, and made production planning more efficient, dropping manual paperwork by 80%. Moreover, the team managed the project smoothly, was timely, and communicated clearly. Overall, Creuto's openness was impressive.

KV

Karan Verma

Project Manager, Galgoties

Read on Clutch

More client voices

/01 of 06

on Clutch
FAQ

Frequently Asked Questions

Straight answers about lending platforms software projects. If yours is not here, ask us directly.

Ask our lending platforms team

It depends on which lifecycle stages are in scope, the number of loan products, bureau and open banking integrations, the sophistication of decisioning, ledger requirements and whether existing loans must be migrated. A single-product MVP is a materially smaller investment than a multi-product lending platform. After discovery we provide a fixed-scope proposal with a clear breakdown.

A validation MVP with one product, digital application and rules-based decisioning typically takes 10 to 14 weeks. A production platform covering origination, servicing and collections usually takes four to seven months. Enterprise or multi-product platforms with embedded lending APIs and loan migration are delivered in phases over eight to fourteen months.

Yes. Our decision engines store every input, rule and model version with the outcome and reason codes, so you can issue adverse action notices, answer complaints and evidence fair lending reviews. We support AML and KYC, consumer credit rules, RBI digital lending directions and GDPR obligations depending on your markets.

Yes. We integrate Experian, Equifax, TransUnion, CIBIL, SIMAH and other bureaus, plus open banking providers such as Plaid and TrueLayer and India's Account Aggregator network, so decisions can use both credit history and real transaction data.

Lending app development usually means the borrower-facing mobile or web app. Lending software development covers the whole system: origination workflows, decision engine, bureau and banking integrations, loan ledger, servicing, collections, underwriting tools and reporting. We deliver both as one connected platform.

Yes. We build buy now pay later products with instant point-of-sale decisions, merchant checkout plugins and APIs, instalment schedules, card and bank repayments, merchant settlement and the consumer credit controls now expected of BNPL lenders.

Yes. Products, rates, fees, terms, documents and decision rules are configurable, so your team can launch personal, SME, secured or point-of-sale products on the same platform.

Yes. We build marketplace lending platforms with borrower applications, investor onboarding and KYC, loan listing and funding, automated repayments distribution and investor reporting, designed around the regulations for P2P lending in your market.

LET'S BUILD

Planning a lending platforms product? Let's scope it together.

Tell us what you are building. We will help you scope it, design it, and ship it, with a senior team accountable end to end.

  • Reply within one business day
  • NDA on request
  • Senior engineers only
  • Fixed scope, no surprises