Creuto is now an OpenAI Select Partner Read More

Banking & Financial Services · Specialisation

Digital Wallet App Development Services

Store, Send, and Spend Money in a Few Taps.

We build digital wallet apps for fintechs, retailers, and super-apps, with secure top-ups, peer-to-peer transfers, QR and NFC payments, rewards, and the KYC and limits regulators require.

  • PCI DSS, AML and tiered KYC built in
  • UPI, Apple Pay, Marqeta and Network International integration
  • Senior wallet and ledger engineers

Plan your digital wallets project

Tell us what you want to build. A senior engineer, not a sales script, replies within one business day.

What's your budget range?

Your idea is protected. NDA available on request.

Trusted by teams building what's next

  • Creuto client 1
  • Creuto client 2
  • Creuto client 3
  • Creuto client 4
  • Creuto client 5
  • Creuto client 6
  • Creuto client 7
  • Creuto client 8
  • Creuto client 9
  • Creuto client 10
  • Creuto client 11
  • Creuto client 12
  • Creuto client 13
  • Creuto client 14
OVERVIEW

Software shaped around how digital wallets really works.

Digital wallets have become everyday payment tools, from splitting a bill and topping up a phone to paying in store with a QR code or tap. Users expect money to move instantly, balances to be correct to the last cent and help to be available in the app when something goes wrong. One incorrect balance or failed transfer can undo years of earned trust.

As a digital wallet app development company, we build wallets as financial systems first and apps second. A double-entry ledger records every top-up, transfer, payment, fee and refund, idempotent processing prevents duplicates, and automated reconciliation matches the ledger with banks, card processors and payment providers such as Network International, Razorpay, Stripe and Adyen every day.

Regulatory controls are part of the design. Tiered KYC with Onfido, Sumsub or Jumio sets limits by verification level, AML transaction monitoring and sanctions screening run in real time, PCI DSS governs card top-ups and issued cards, and stored-value rules from the RBI prepaid payment instrument directions, CBUAE stored value facilities regulation, SAMA or the FCA e-money regime shape safeguarding and limits.

Whether you are launching a standalone e-wallet, adding a wallet to a retail or ride-hailing super-app, issuing prepaid cards through Marqeta, or building a UPI or remittance app, we deliver wallet software that users trust with their money and operations teams can run, with loyalty, bill payments and partner services added as you grow.
Why digital wallets teams build with Creuto

Ledger-first architecture

A double-entry ledger with idempotent posting, holds and reversals, so every balance can be traced to its transactions and reconciled with banks and providers daily.

Instant P2P transfers

Send money by phone number, contact, username or QR code, with request, split and scheduled payments and real-time notifications for both parties.

QR and NFC payments

Merchant QR acceptance on UPI and local schemes, tap-to-pay with tokenised cards through Apple Pay and Google Pay, and online checkout from the wallet.

Tiered KYC and limits

Start users with minimal verification and low limits, then step up through document and liveness checks, with limits enforced per tier, product and corridor.

Real-time AML and fraud monitoring

Velocity rules, device intelligence, sanctions screening and behavioural scoring on every transaction, with case management for investigators.

Rewards and engagement

Cashback, points, referral rewards and offers funded by merchants or the programme, accounted for correctly in the ledger.

0+

Products delivered

0+

Years of engineering

0%

Client satisfaction

0+

Industries served

0+

Countries with live products

WHAT WE BUILD

Digital Wallets software solutions we build.

Each one designed with your teams, integrated with the systems you already run, and engineered to scale.

RELATED AREAS

More Banking & Financial Services software we build

Other banking & financial services areas with a dedicated page.

TYPES OF SOLUTIONS

Types of digital wallets apps and software we develop.

The product categories digital wallets organisations most often ask us to build, from focused mobile apps to multi-tenant platforms.

  1. 01

    Mobile wallet apps

    Standalone e-wallets with top-ups, transfers, payments and withdrawals on iOS and Android.

  2. 02

    UPI payment apps

    UPI-based apps for P2P and merchant payments in India, built through sponsor bank partnerships.

  3. 03

    P2P payment apps

    Send, request and split money between friends with instant settlement and social features.

  4. 04

    Super-app wallets

    Wallet modules embedded in ride-hailing, retail, telecom or delivery apps.

  5. 05

    Prepaid card and wallet programmes

    Wallets with virtual and physical prepaid cards issued through processors such as Marqeta.

  6. 06

    Merchant and QR acceptance apps

    Merchant onboarding, QR display, payment notifications and settlement for small businesses.

  7. 07

    Remittance and cross-border wallets

    Multi-currency balances, FX and transfers to bank accounts, wallets and cash pick-up.

  8. 08

    Closed-loop retail wallets

    Store wallets with stored value, loyalty and gift balances for retailers and campuses.

  9. 09

    Corporate expense and payroll wallets

    Employee wallets for salaries, allowances and expenses with employer controls.

KEY FEATURES

Must-have features of a digital wallets platform we build in.

Grouped by who uses them. Every feature below is one we have shipped to production, not a wishlist.

/01

Wallet user app

Everyday money in a few taps.

  • Quick sign-up with tiered KYC
  • Top-up by card, bank and cash
  • Send, request and split money
  • Scan-to-pay QR and tap-to-pay
  • Bill payments and mobile recharge
  • Virtual and physical prepaid cards
  • Rewards, cashback and referrals
  • Transaction history and disputes
/02

Merchant and agent tools

For merchants and cash-in agents.

  • Merchant onboarding and KYB
  • Static and dynamic QR codes
  • Payment notifications and sound box support
  • Daily settlement and statements
  • Refunds and partial refunds
  • Agent cash-in and cash-out
  • Staff accounts and roles
  • Sales reports and payouts
/03

Admin and compliance console

Control the programme and the money.

  • Ledger explorer and balance audits
  • Daily reconciliation and breaks
  • KYC tier and limit configuration
  • AML monitoring rules and cases
  • Fee, cashback and promotion setup
  • Safeguarding and float reports
  • Regulatory and suspicious activity reports
  • Audit logs and maker-checker approvals
CHALLENGES WE SOLVE

What holds digital wallets teams back.

The problems we most often help digital wallets organisations solve, and design every engagement around.

  1. 01

    Trust and security

    Users need confidence that their money and data are protected, and a single account takeover or wrong balance can damage the brand for good.

  2. 02

    Regulatory limits and licensing

    Wallets must enforce KYC tiers, balance and transaction limits, safeguarding and monitoring rules that differ by market and licence type.

  3. 03

    Ledger accuracy

    Every balance and transaction must reconcile exactly across top-ups, transfers, fees, refunds and chargebacks, even when providers fail mid-flow.

  4. 04

    Fraud and mule accounts

    Low-friction onboarding attracts fraudsters, mule accounts and promotion abuse that need real-time detection without blocking genuine users.

  5. 05

    Building a network

    A wallet is only useful if friends and merchants accept it, so onboarding, incentives and interoperability matter as much as features.

SELECTED WORK

Products we have shipped. Results we can point to.

Real products designed and engineered by Creuto end to end, with the operational depth banking & financial services and digital wallets projects demand.

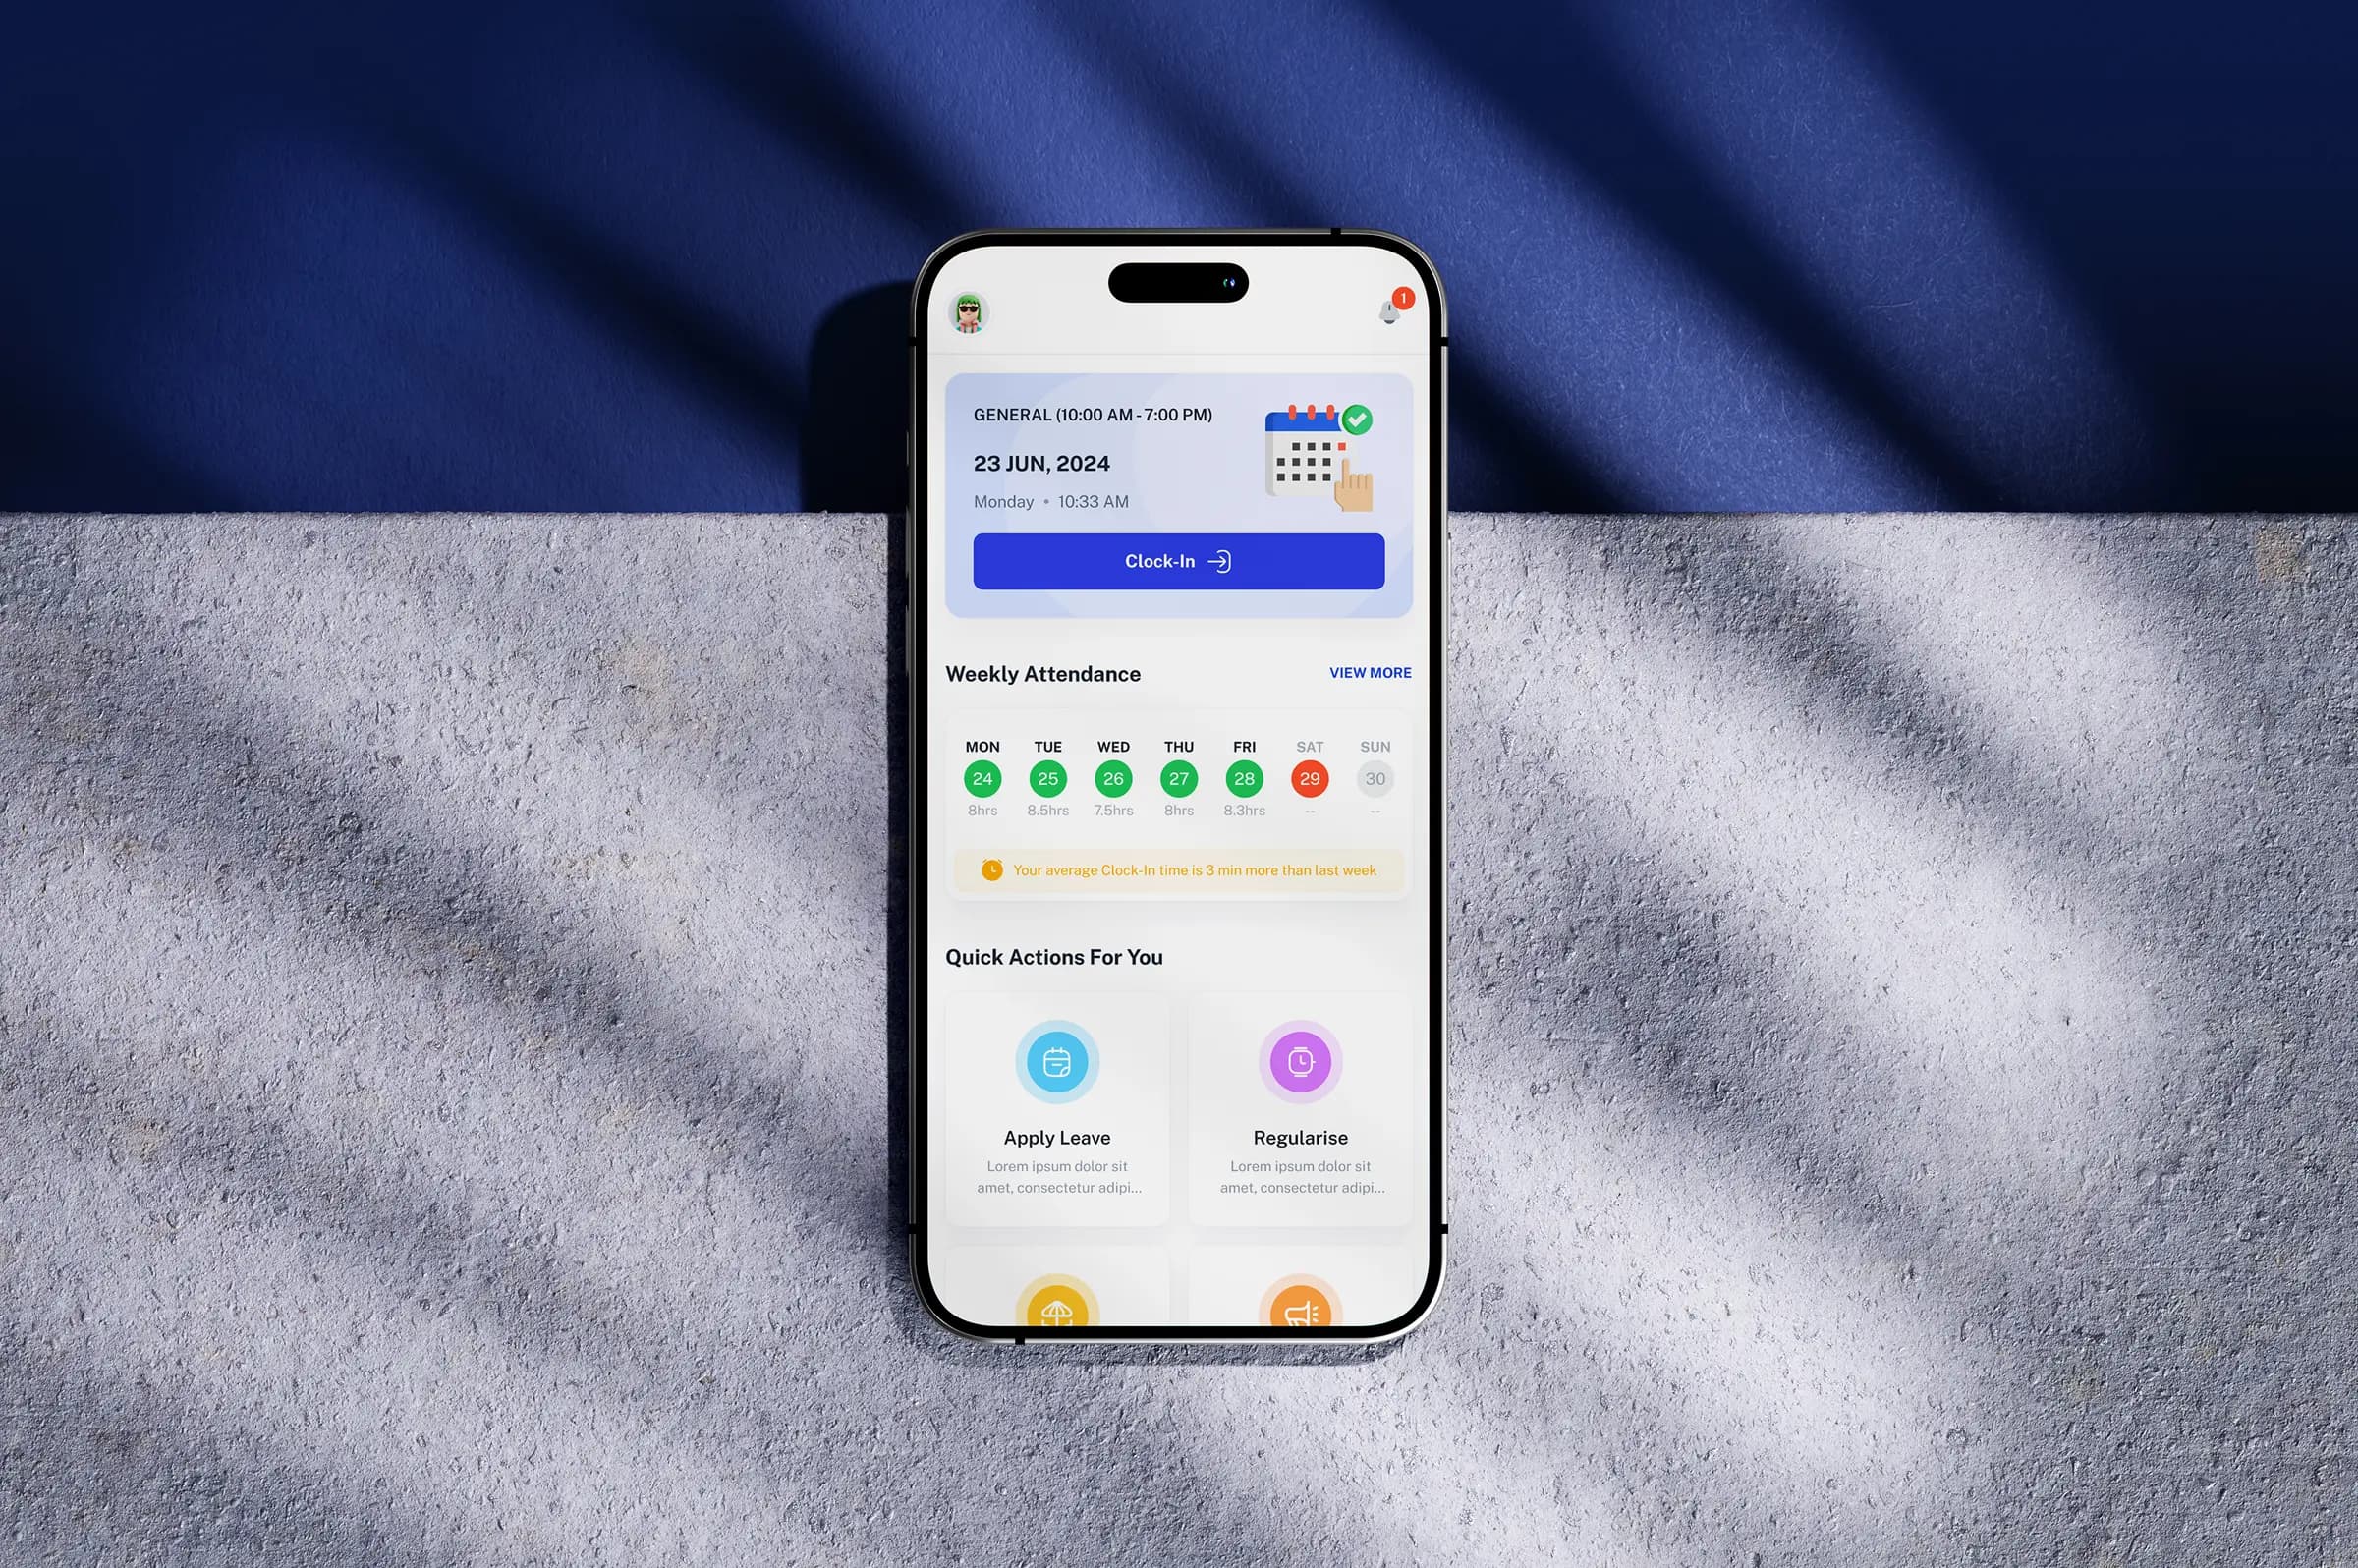
Enterprise HR & Payroll Platform – Nomina
/01 · HR & Payroll

Enterprise HR & Payroll Platform – Nomina

A complete, end-to-end HR and payroll platform covering employee onboarding to exit, attendance, leave, payroll processing, compliance, and reporting — built and delivered by Creuto from scratch.

5×

Faster Payroll Processing

20 wk

Time to Market

5

User Roles

View Case Study
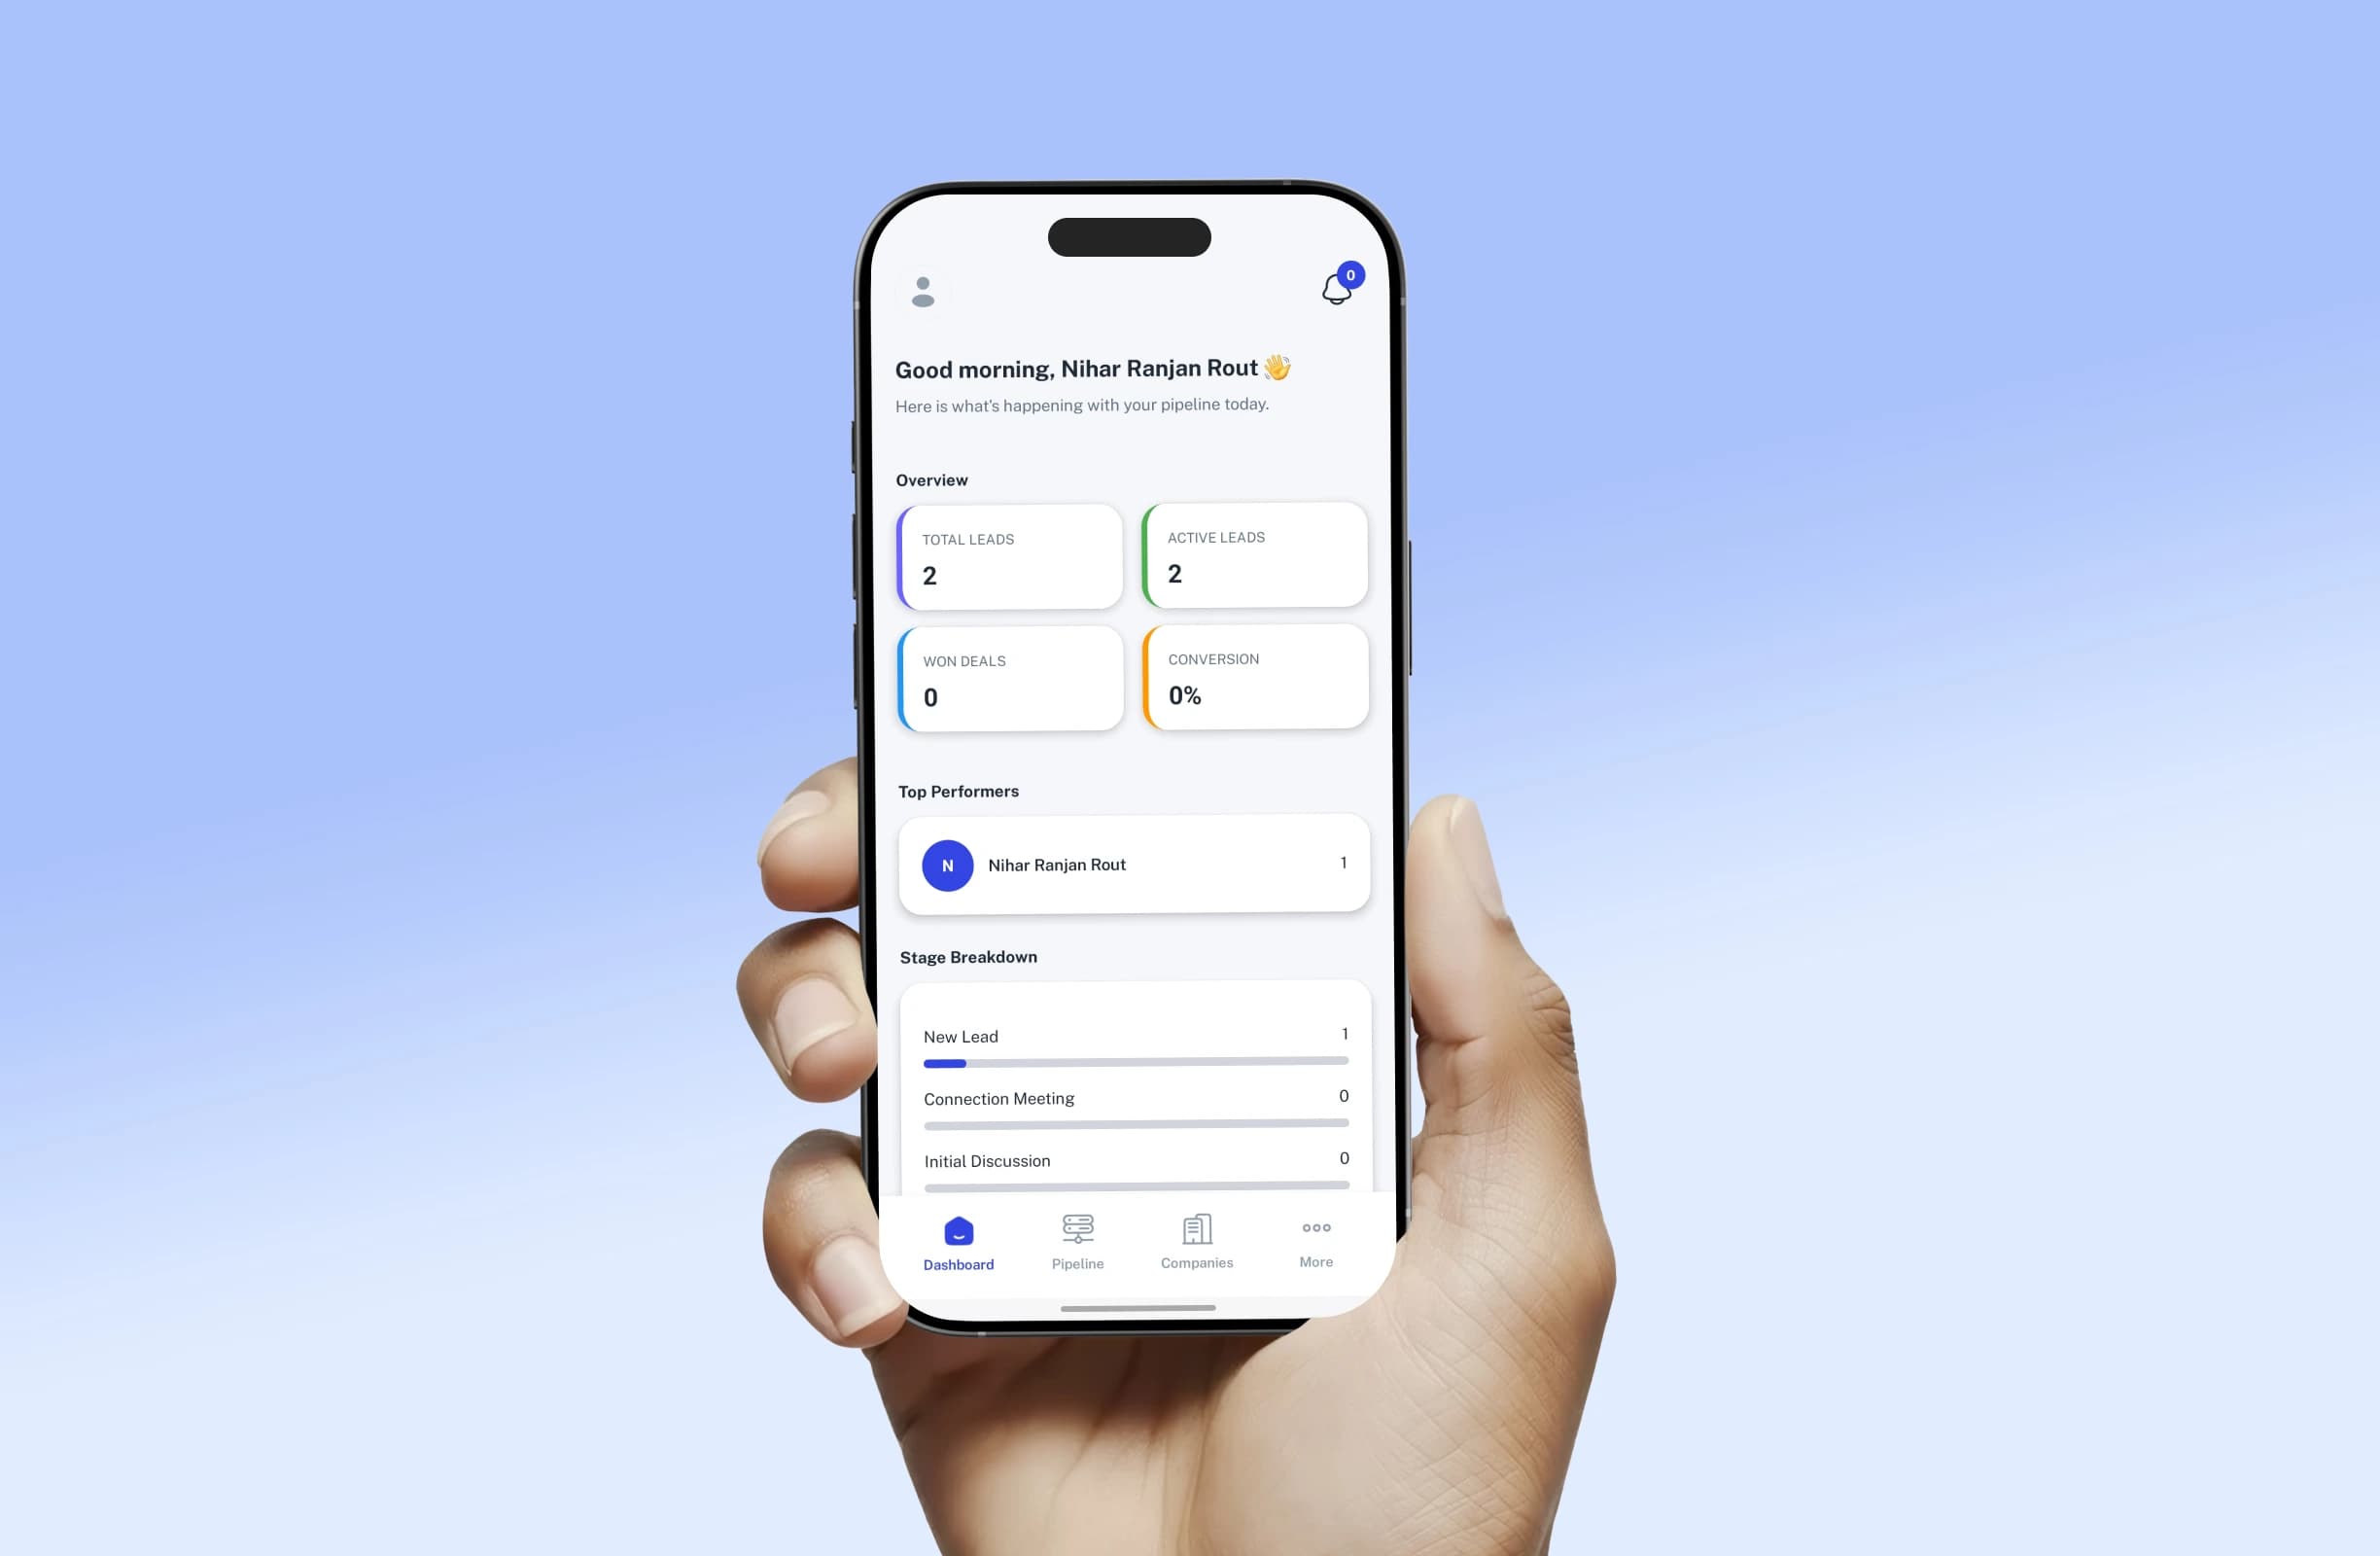
AI-Powered CRM & Sales Engagement Platform
/02 · Sales / CRM

AI-Powered CRM & Sales Engagement Platform

A complete Before-Sales and After-Sales CRM platform — AI-powered market insights, Kanban pipeline management, complaint tracking, and role-based dashboards built and delivered by Creuto end to end.

2

CRM Modules (Before & After)

AI

Market Intelligence Engine

360°

Customer Lifecycle Coverage

View Case Study
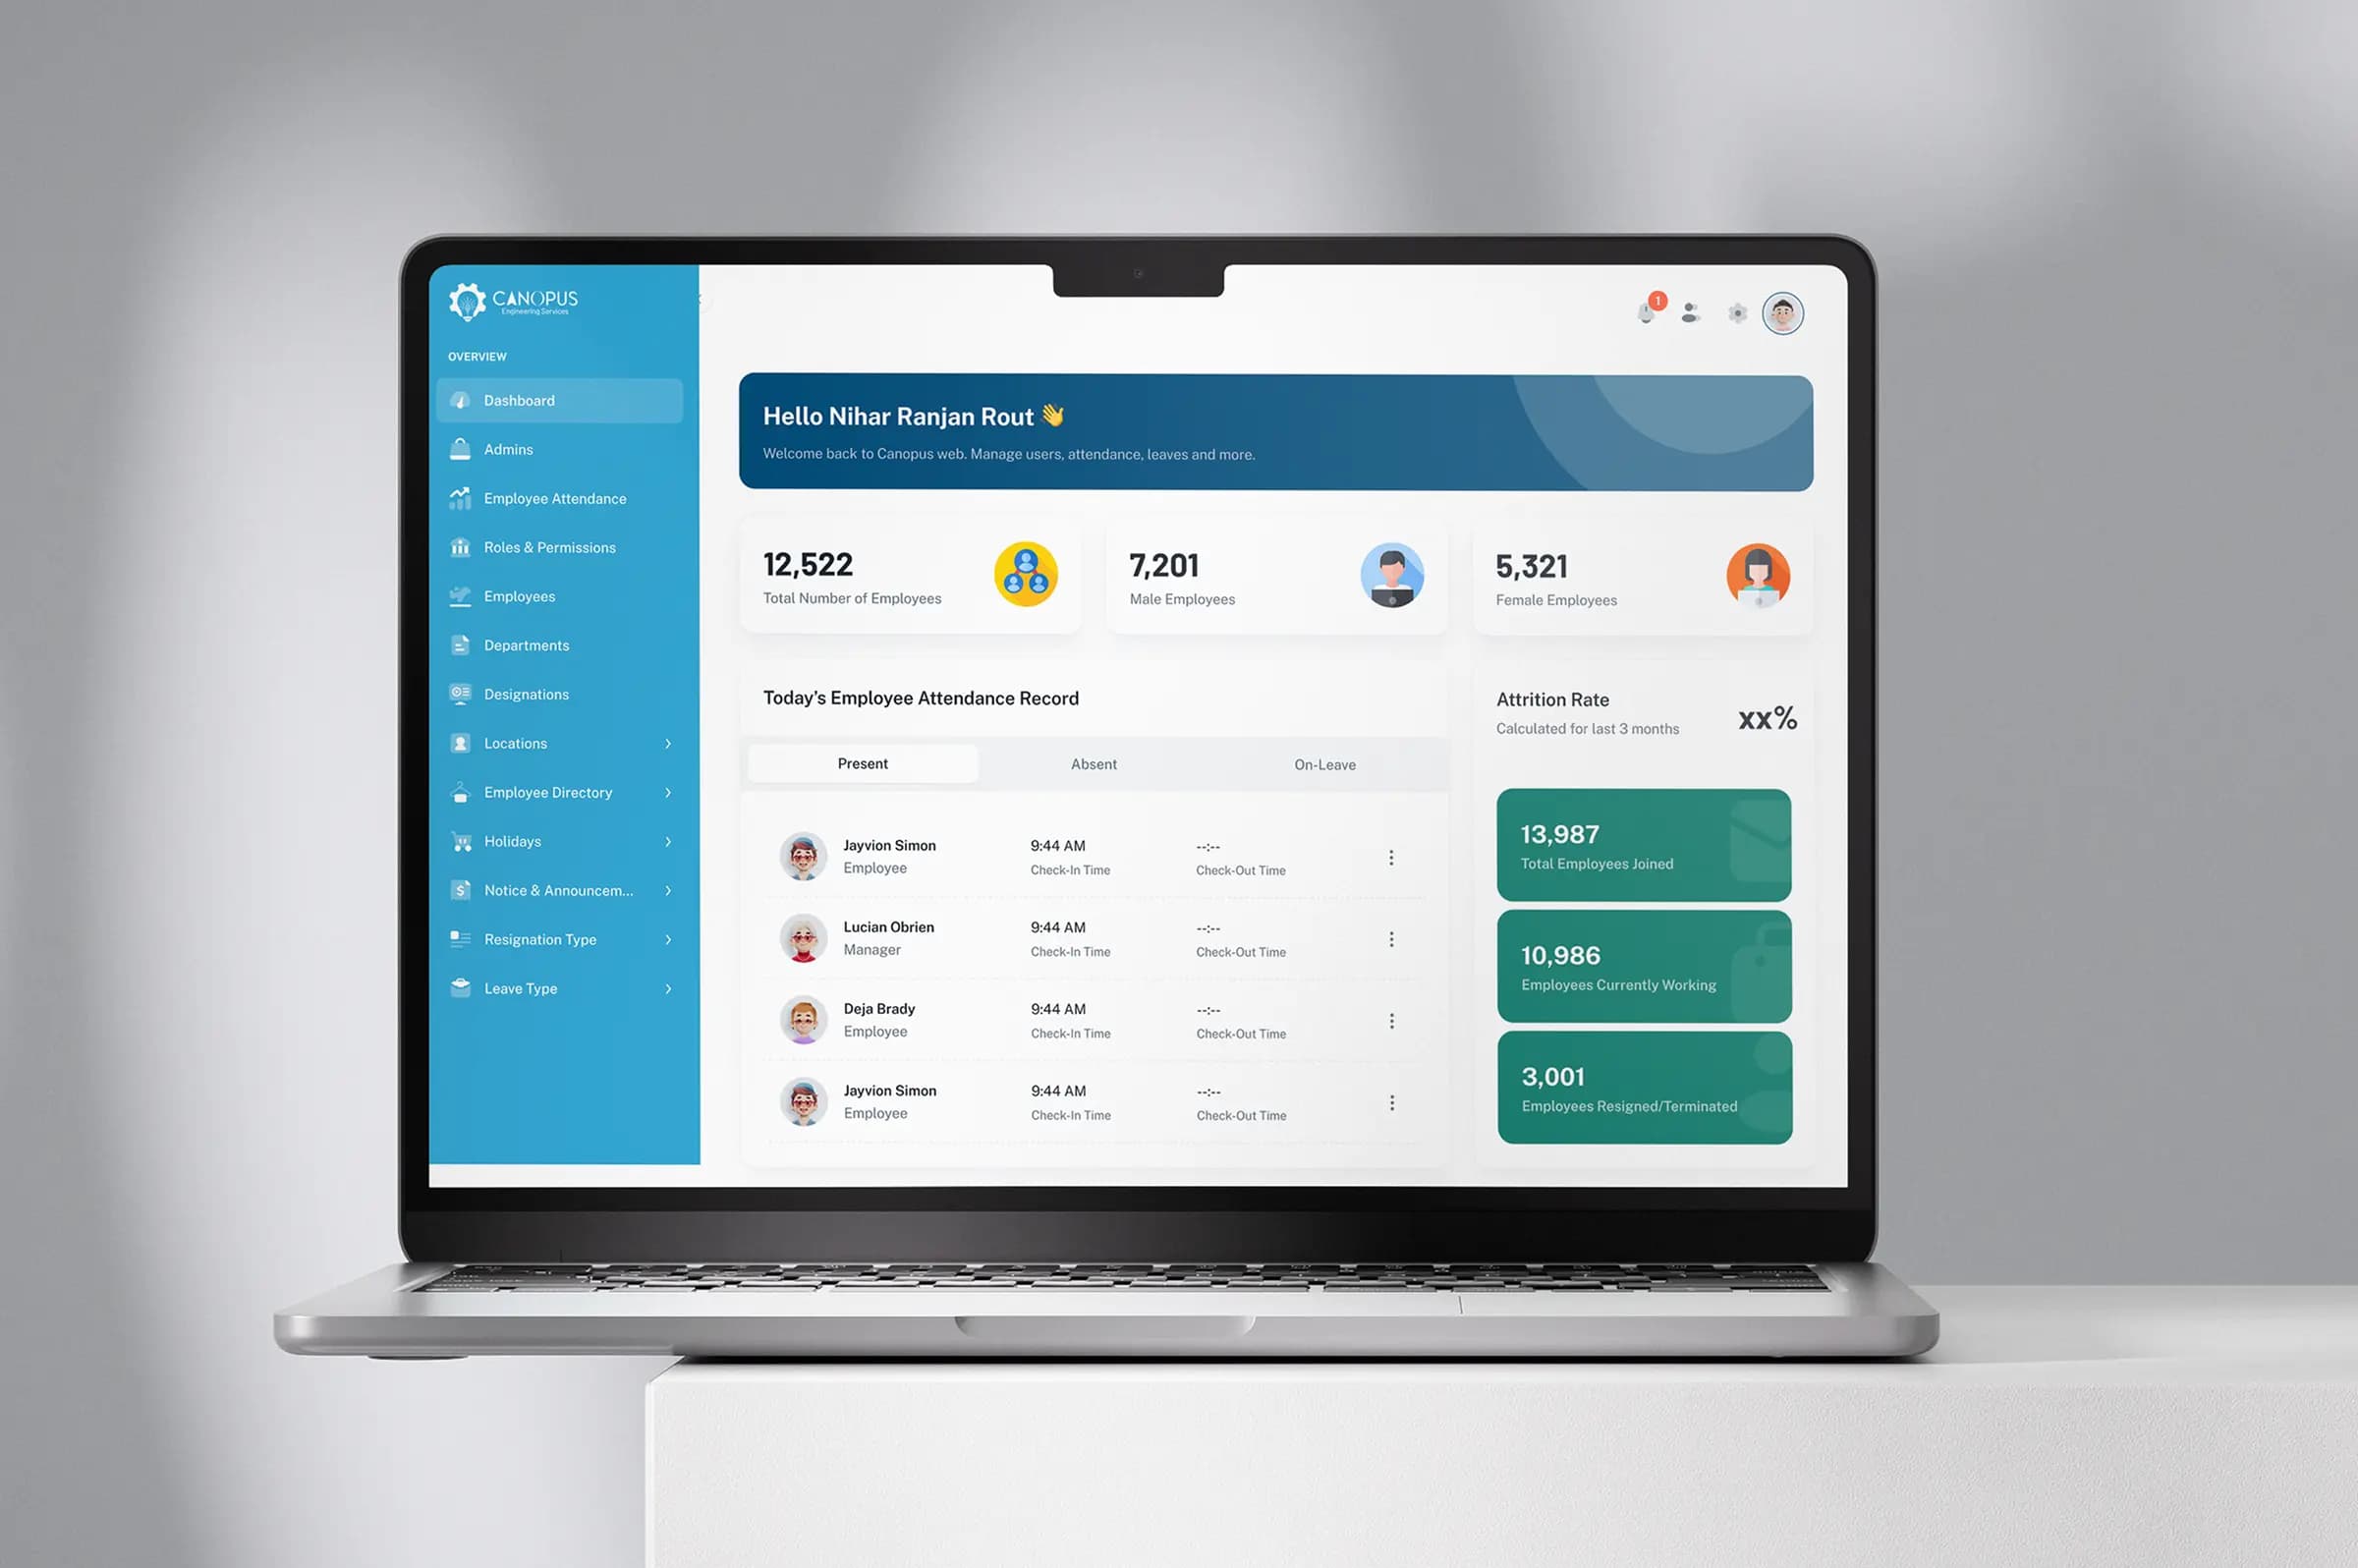
Custom Cloud ERP for Large-Scale Industrial Operations
/03 · Enterprise ERP

Custom Cloud ERP for Large-Scale Industrial Operations

A fully custom, browser-based ERP system built to unify every department, eliminate silos, and scale with the business — designed and delivered by Creuto end to end.

4

Departments Unified

1

Source of Truth

100%

Browser-Based Access

View Case Study
COMPLIANCE AND SECURITY

Compliance and security, designed in.

The digital wallets standards we build against and the controls behind them. Your compliance team keeps ownership; we make the software easy to certify.

Wallet regulations we build for

  • RBI prepaid payment instrument directions and NPCI UPI rules (India)
  • CBUAE stored value facilities regulation (UAE)
  • SAMA payment services and e-wallet rules (Saudi Arabia)
  • FCA e-money and safeguarding rules (UK)
  • PSD2 and SCA (EU and UK)
  • AML, KYC and CFT obligations including FATF guidance
  • PCI DSS v4.0 and GDPR

Payment standards and protocols

  • UPI and BharatQR specifications
  • EMVCo QR code specification
  • EMV payment tokenisation
  • ISO 8583 card messaging
  • ISO 20022 for account transfers
  • 3-D Secure 2 for card top-ups

Security controls

  • Device binding and SIM change detection
  • Biometric and PIN authentication
  • Tokenisation of stored cards
  • Encryption with HSM-backed keys
  • Tamper-evident ledger and audit trails
  • Runtime app protection
  • Penetration testing before launch

Platform quality

  • SOC 2 and ISO/IEC 27001 aligned controls
  • Idempotent, exactly-once posting
  • Automated daily reconciliation
  • Load testing for festival and salary peaks
  • Disaster recovery with tested failover
  • Accessibility to WCAG 2.2 AA
INTEGRATIONS

Digital Wallets integrations we connect.

The platforms, standards and third-party services a product in this sector usually has to talk to. If yours is not listed, it is almost certainly something we have connected before.

/01Payments and cards

  • Network International
  • Razorpay
  • Stripe
  • Adyen
  • Checkout.com
  • Marqeta
  • Apple Pay and Google Pay

/02Banking rails

  • UPI via sponsor banks
  • IMPS and NEFT
  • Faster Payments
  • SEPA Instant
  • UAE Instant Payment Platform (Aani)
  • Saudi sarie

/03Identity, KYC and risk

  • Onfido
  • Sumsub
  • Jumio
  • Plaid
  • Sardine
  • ComplyAdvantage

/04Engagement and billers

  • Twilio
  • Firebase Cloud Messaging
  • WhatsApp Business API
  • BBPS billers (India)
  • Telecom top-up aggregators
  • Braze
WHY CREUTO

Why choose Creuto as your digital wallets software development company

The reasons clients in this sector give when they recommend us, not the ones we would pick ourselves.

Either we build it exceptional, or we don't.

The standard every digital wallets product leaves our studio with.

0+

Products delivered

0+

Years of engineering

0%

Client satisfaction

Start a conversation
  1. /01

    Ledger before screens

    We design the money model first, so balances are correct and auditable from the first transaction.

  2. /02

    Experience with local rails

    UPI, instant payment schemes, card processors and wallets in the Gulf, India, UK and EU are integrations we build regularly.

  3. /03

    Compliance built into flows

    KYC tiers, limits and monitoring are enforced by the platform, with evidence for your regulator and auditors.

  4. /04

    Designed for everyday use

    Fast, simple payment flows tested with real users, because wallets live or die on daily habit.

  5. /05

    Ready for scale and partners

    Multi-tenant and modular design lets you embed the wallet in partner apps and add new markets.

BENEFITS

Benefits of custom digital wallets software over off-the-shelf tools.

What organisations in this sector gain when the software is built around their workflows rather than the other way around.

  1. 01

    Higher customer engagement

    A wallet in your app brings users back for everyday payments, transfers and rewards.

  2. 02

    Lower payment costs

    Closed-loop and account-to-account payments reduce reliance on card fees for many transactions.

  3. 03

    Accurate, auditable balances

    A double-entry ledger and daily reconciliation remove balance disputes and month-end surprises.

  4. 04

    First-party payment data

    Wallet transactions give insight into customer behaviour that informs offers and products.

  5. 05

    New revenue lines

    Bill payments, cards, remittances and partner services become possible on the same platform.

  6. 06

    Controlled fraud losses

    Real-time monitoring and tiered limits keep fraud and promotion abuse in check.

HOW WE WORK

Our digital wallets software development process.

Transparent, sprint-based and built around decisions you can see. You know what ships, when, and why at every step.

Start Your Project
  1. 01

    Wallet and licence discovery

    We map the use cases, licence type, markets, funding and withdrawal methods, and measures such as activation, transaction success rate and cost per transaction.

  2. 02

    Ledger and compliance architecture

    Ledger model, account structure, safeguarding, KYC tiers, limits, monitoring rules and hosting region are designed before any screen is drawn.

  3. 03

    Design and user validation

    Sign-up, transfer and payment flows are tested with real users, including failed top-ups, wrong recipients, disputes and lost phones.

  4. 04

    Agile engineering

    Two-week sprints against sandbox bank, card and KYC environments, with every money movement covered by ledger and idempotency tests.

  5. 05

    Integration, QA and hardening

    Reconciliation against real provider files, chaos tests for provider failures, load testing for peak days and a penetration test.

  6. 06

    Phased launch and growth

    Launch to staff and a closed cohort, then open up with monitoring, fraud tuning and a roadmap driven by activation and transaction data.

TECHNOLOGY STACK

Technology stack for digital wallets software development.

Chosen per project for longevity, hiring depth and fit with your existing systems, never by fashion.

/01Mobile

  • Swift
  • SwiftUI
  • Kotlin
  • Jetpack Compose
  • Flutter
  • React Native

/02Web and backend

  • React
  • Next.js
  • TypeScript
  • Node.js
  • NestJS
  • Java
  • Spring Boot
  • Go

/03Payments and ledgers

  • Double-entry ledger
  • Kafka
  • Temporal
  • Apple Pay
  • Google Pay
  • ISO 20022
  • Webhooks

/04Data

  • PostgreSQL
  • Redis
  • ClickHouse
  • BigQuery
  • Snowflake

/05Cloud and DevOps

  • AWS
  • Azure
  • Google Cloud
  • Docker
  • Kubernetes
  • Terraform
  • GitHub Actions

/06AI and risk

  • Scikit-learn
  • PyTorch
  • Claude
  • OpenAI
  • pgvector

/07Security and identity

  • OAuth 2.0
  • OpenID Connect
  • Keycloak
  • AWS KMS
  • Vault

AI IN DIGITAL WALLETS

AI that spots the mule, and serves the user.

We use AI in wallets where it stops fraud, scams and mule activity in real time and answers user questions instantly, with investigator review on high-risk decisions and every action logged.

Explore our AI engineering
  • Real-time transaction and scam risk scoring
  • Mule account and network detection
  • Promotion and referral abuse detection
  • Support assistant for payments and disputes
  • Personalised offers and cashback targeting
  • KYC document and selfie checks
TRENDS

Trends shaping digital wallets software right now.

The shifts we design for so a product launched this year is still the right product in three.

  1. 01

    Instant account-to-account payments

    UPI, Aani in the UAE, sarie in Saudi Arabia and Pix show wallets increasingly sitting on top of instant bank rails.

  2. 02

    Super-app consolidation

    Ride-hailing, delivery, telecom and retail apps are adding wallets to own the payment relationship.

  3. 03

    Cross-border interoperability

    Links between instant payment systems, such as UPI connections with other countries, are making wallet-to-wallet remittances cheaper.

  4. 04

    Stricter KYC and mule account controls

    Regulators are tightening onboarding and monitoring as wallets become channels for scams and money mules.

  5. 05

    Tokenised and tap-to-pay everywhere

    Network tokens, NFC on more devices and SoftPOS make tap-to-pay from wallets a standard expectation.

COST AND TIMELINE

How much does digital wallets software development cost?

There is no honest single number. Scope, integrations and compliance drive the budget, so we price against a written scope after discovery. The factors below are what move it.

  1. 01

    Licence and partner model

    Operating on your own e-money licence requires more controls and reporting than working through a regulated partner.

  2. 02

    Funding and withdrawal methods

    Each card, bank rail, cash agent and payout method adds integration and reconciliation.

  3. 03

    Card issuing

    Virtual and physical cards add processor integration, tokenisation and scheme work.

  4. 04

    Markets and currencies

    Each market adds KYC rules, limits, rails and data-residency requirements.

  5. 05

    Merchant network

    Merchant onboarding, QR acceptance, settlement and agent networks are a product of their own.

  6. 06

    Fraud and AML tooling

    Real-time monitoring, device intelligence and case management add data and model effort.

EngagementTypical scopeTimeline
Validation MVPWallet app with tiered KYC, card top-up, P2P transfers, ledger and reconciliation through one regulated partner.10 to 14 weeks
Production wallet platformQR and NFC payments, bank rails, bill payments, merchant tools, AML monitoring and admin console.4 to 7 months
Enterprise or multi-market walletCard issuing, remittances, multi-currency, super-app embedding, agent network and AI fraud scoring.8 to 14 months, phased
BUSINESS MODELS

How digital wallets products make money.

Revenue models we have built billing, reporting and growth loops for. Most products combine two or three.

  1. 01

    Merchant discount fees

    A fee on payments accepted by merchants through the wallet.

  2. 02

    Interchange on issued cards

    Revenue share on spending with wallet-linked prepaid or debit cards.

  3. 03

    Transfer, FX and withdrawal fees

    Charges on cross-border transfers, currency conversion and cash withdrawals.

  4. 04

    Bill payment and recharge commissions

    Commission from billers and telecom operators on payments made in the app.

  5. 05

    Float and partner revenue

    Returns on safeguarded balances where permitted, and referral income from financial products.

HOW WE DELIVER

Services behind our digital wallets work

The engineering disciplines every project in this sector draws on. Each has its own page with process, stack and FAQs.

TESTIMONIALS

Don't take our word for it.

Founders and product leaders on what it is like to build with Creuto.

“Their ability to adapt to our needs while keeping things on track made the experience seamless.”

Creuto delivered a scalable system that improved payroll efficiency and transparency and reduced human errors. The team adhered to timelines, quickly responded to changes, adapted to needs, and managed the project professionally. Their ability to understand the client's requirements was impressive.

RM

Radhika Mohanty

Finance Manager, Crect

Read on Clutch

More client voices

/01 of 06

on Clutch
FAQ

Frequently Asked Questions

Straight answers about digital wallets software projects. If yours is not here, ask us directly.

Ask our digital wallets team

It depends on your licence and partner model, the funding and withdrawal methods, card issuing, the markets and currencies you support, merchant acceptance and the depth of fraud and AML tooling. A single-market MVP through a regulated partner is a materially smaller investment than a multi-market wallet. After discovery we provide a fixed-scope proposal with a clear breakdown.

A validation MVP with tiered KYC, top-ups, P2P transfers and a ledger typically takes 10 to 14 weeks. A production platform with QR and NFC payments, bank rails and merchant tools usually takes four to seven months. Enterprise or multi-market wallets with card issuing and remittances are delivered in phases over eight to fourteen months.

It depends on the market. India requires RBI prepaid payment instrument authorisation and NPCI rules for UPI, the UAE has CBUAE stored value facilities regulation, Saudi Arabia has SAMA payment services rules and the UK and EU have e-money and PSD2 regimes. All require AML and KYC controls. Many clients start through a licensed partner.

We integrate Network International, Razorpay, Stripe, Adyen, Checkout.com and Marqeta, Apple Pay and Google Pay, and bank rails including UPI through sponsor banks, IMPS, Faster Payments, SEPA Instant, Aani in the UAE and sarie in Saudi Arabia.

Wallet app development usually means the user-facing mobile app. Wallet software development covers the full system: ledger, payment and bank integrations, KYC and limits, AML monitoring, merchant tools, reconciliation and the admin console. We deliver both as one connected product.

We use a double-entry ledger where every movement has matching entries, idempotency keys so retries never double-post, holds for pending transactions and automated daily reconciliation with banks and providers, with breaks surfaced for operations immediately.

Yes. We build wallets as standalone apps or as modules and SDKs inside existing apps, sharing identity and design with the host app while keeping the ledger and compliance controls separate.

Yes. We build multi-currency wallets with separate balances per currency, FX conversion through a partner, cross-border transfers and ledgers that report positions by currency.

LET'S BUILD

Planning a digital wallets product? Let's scope it together.

Tell us what you are building. We will help you scope it, design it, and ship it, with a senior team accountable end to end.

  • Reply within one business day
  • NDA on request
  • Senior engineers only
  • Fixed scope, no surprises