Custom investment software development: SEBI's 2026 draft
SEBI's draft 2026 PMS rules change what custom investment software development must model. What to build now, and what to leave configurable until notified.
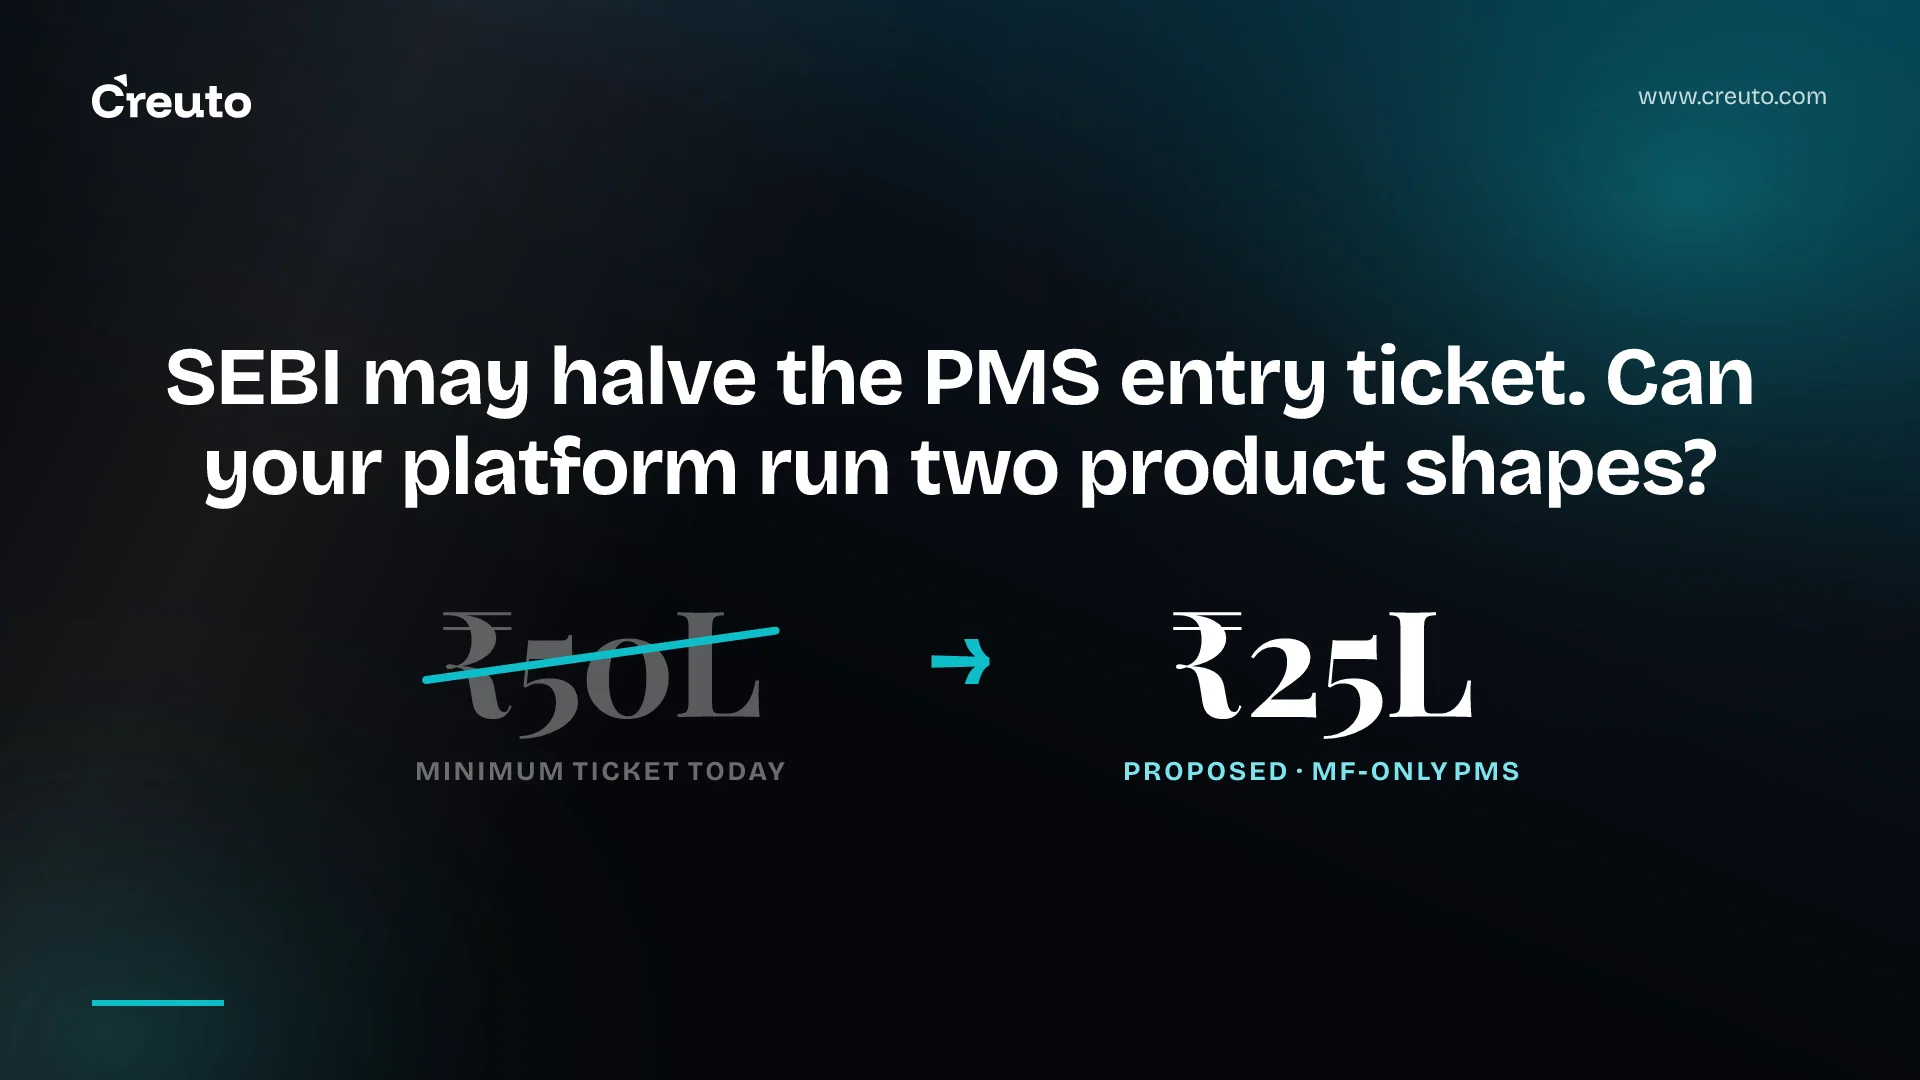
Most conversations about custom investment software development start with features — dashboards, reporting, a client app. For a SEBI-registered portfolio manager that is the wrong end of the problem. The regulations already specify a large part of the system: how a fee may be computed, what a client must be offered at onboarding, what has to be disclosed and where, and what an auditor will check. Get those wrong and no amount of interface polish saves the product.
There is also a reason to look at this now rather than next year. SEBI has consulted on a comprehensive review of the Portfolio Managers Regulations, 2020, alongside a draft set of Portfolio Managers Regulations, 2026. Public comments closed on 13 August 2026. Nothing below described as proposed is law yet, and the distinction matters for what you build today.
The rules are most of the specification
Four requirements in SEBI's current Master Circular for Portfolio Managers shape the software more than any feature request will.
Performance fees run on a high water mark
Performance or profit-sharing fees must be computed on the high water mark principle over the life of the investment — the highest value the portfolio has previously reached — and charged only on the increase above it. The frequency of charging cannot be less than quarterly.
This is the single most common place a generic platform fails. A high water mark is per client, persists across years, survives partial withdrawals and additional contributions, and has to be reconstructible on any historical date when a client disputes an invoice. That is a ledger with an audit trail, not a column on an account record. If you are evaluating an off-the-shelf product, ask to see how it recomputes a fee for a client who added funds mid-year after a drawdown. The answer tells you most of what you need to know.
Direct onboarding must be offered, and it must be visible
Portfolio managers must give clients the option to be onboarded directly, without a distributor in between, and must disclose that option prominently in the Disclosure Document, in marketing material and on the website. No charges apply at direct onboarding.
In software terms that is two onboarding paths with different fee treatment, from day one — not a toggle added when someone asks. Distribution also brings its own obligation: portfolio managers must ensure anyone distributing their services is registered with APMI, which means the platform needs to hold and check that registration rather than store a name in a text field.
The minimum ticket is a validation rule
The first single lump-sum investment received from a client, as funds or securities, must not be less than ₹50 lakh. And portfolio managers must not organise portfolios as 'Schemes' akin to mutual fund schemes when marketing to clients — which constrains how the product is presented as much as how it is built.
Strategy changes are audited
Changes to a strategy or its benchmark must be recorded with proper justification and are verified as part of the annual audit. That is a versioned record with a reason attached, not an edit in place. Systems that let an administrator change a benchmark without capturing who, when and why create an audit finding rather than a feature.
What the draft 2026 regulations would change
SEBI's consultation paper puts several proposals out for comment. The headline is a new, lighter category. Treat all of this as proposed:
| Area | Today | Proposed |
|---|---|---|
| Minimum client investment (Mutual Fund-only PMS) | ₹50 lakh | ₹25 lakh |
| Minimum net worth (Mutual Fund-only PMS) | ₹5 crore | ₹2 crore |
| Management fee under that framework | — | Fixed fee capped at 2.5% of AUM |
| Unlisted debt under discretionary services | Not permitted | Up to 10% of client AUM, investment grade |
| Foreign securities | Not permitted | Permitted |
| 'To be listed' securities | Unclear | Specifically permitted |
The consultation also proposes a simplified disclosure document as part of a paperless initiative, with the latest version required to be available on the website, simplified certification for the Principal Officer, and a 12-month compliance window for existing portfolio managers from the commencement of the regulations. For context on why SEBI is revisiting this at all, the paper notes PMS industry assets under management have reached ₹42.61 lakh crore.
What to build now, and what to leave configurable
The useful question is not whether these proposals pass. It is which of them, if they pass, would force a rewrite rather than a configuration change. Three answers:
- Build the fee engine to support multiple schedules from the start. A fixed management fee capped at a percentage of AUM, alongside a high water mark performance fee, is two fee types coexisting for different client categories. Hard-coding one fee model is the mistake that costs a rewrite. Whether the cap is 2.5% or another number is a configuration value.
- Make the instrument model multi-currency and multi-venue now. If foreign securities become permissible, a platform that assumed a single currency and a domestic custodian has a data migration on its hands, not a settings change. Currency, venue and custodian belong in the holdings model whether or not you use them yet.
- Keep client category as a first-class attribute. A lighter Mutual Fund-only category with a different minimum, a different fee cap and different disclosures means one platform serving two product shapes with different validation rules. That is an attribute the whole system branches on, and it is much cheaper to introduce before there is production data than after.
Everything else — thresholds, percentages, form formats, disclosure templates — should be data you can change without deploying. Indian compliance moves, and it moves on its own schedule. We have made the same argument about payroll systems facing a replaced statutory form and about rules that now vary per state: the systems that survive are the ones where a rule is a record.
Custom investment software development: build or buy
Ready-made PMS platforms exist and they are a reasonable choice for a firm running a standard discretionary book. The honest test is whether your process differs from the standard workflow in ways that make you money.
Buy when your differentiation is investment performance and client relationships, your strategies fit conventional mandates, and your fee structures are ordinary. You are purchasing a compliance-maintenance subscription as much as software, and that has genuine value when rules change.
Build when the mismatch is structural: unusual fee arrangements, a proprietary research or allocation process you want in the workflow, multiple regulated entities sharing one client base, or integration with systems that already run your business. Also build when the vendor's roadmap decides when you can launch a product — that constraint tends to cost more than the licence.
The middle path is common and underrated: buy the regulated core for holdings, orders and statements, build the layer that is actually yours. The same reasoning applies whenever a category-leading product meets a non-standard process, which is the argument we made about platform pricing versus a custom CRM.
Why the ledger has to be reconstructible
Almost every obligation above resolves to the same underlying capability: being able to state what a client held, and what it was worth, as at an arbitrary past date. A fee computed on a high water mark needs it. A client statement needs it. An auditor checking a benchmark change needs it. A dispute two years later needs it.
That is harder than it sounds, and it is where platforms built feature-first come apart. Three things break the naive version:
- Corporate actions. Bonuses, splits, mergers and rights issues change the quantity and cost basis of a holding retrospectively. If your system stores a current quantity and overwrites it, every historical valuation before that action is now wrong and you cannot tell which.
- Partial withdrawals and additional contributions. These change the capital base a performance fee is measured against. Handling them correctly against a high water mark is the specific calculation worth writing worked test cases for before any code ships, because it is the one clients check.
- Late and corrected data. Custodian files arrive late and get restated. A ledger that only knows the current truth cannot distinguish "this is what we believed on 31 March" from "this is what we now know about 31 March", and regulated reporting needs both.
The pattern that survives all three is an append-only transaction log with valuations derived from it, rather than balances mutated in place. It costs more in the first month and saves the project in the second year. It is also the difference between answering a regulator's question in an afternoon and rebuilding history from spreadsheets.
How to scope this properly
A realistic first phase for a portfolio management platform is not a feature list. It is the four things a regulator and a client both care about:
- A holdings and transactions ledger that can be reconstructed as at any date, because every report and every fee depends on it.
- A fee engine with the high water mark implemented and tested against worked examples, including contributions and withdrawals.
- Onboarding with both direct and distributor paths, APMI registration checks, and the disclosure document served from one place.
- Client reporting and the audit trail behind it.
Everything else — the mobile app, the analytics, the model portfolios — sits on top of those four and can follow. Teams that build the dashboard first and the ledger second end up rebuilding the dashboard. If you are weighing the spend, the general framing of what custom software returns on the investment applies here with one addition specific to regulated firms: a compliance failure has a cost that a feature gap does not.
The short version
Read the Master Circular before the feature list. Implement the high water mark properly and treat it as a ledger. Offer direct onboarding as a real path, not a checkbox. Then build for two product shapes rather than one, because SEBI has proposed a lighter category and a 12-month compliance window is not long if the answer is a rewrite.
Primary sources, as of September 2026: SEBI's Master Circular for Portfolio Managers dated 16 July 2025, and the consultation paper on the comprehensive review of the Portfolio Managers Regulations. Verify current requirements against SEBI's own publications before making a build decision — and if you want a second opinion on where your process actually differs from the standard, that is a conversation our custom software team has regularly with regulated firms.
Frequently asked questions
At minimum: a holdings and transactions ledger reconstructible as at any date, a fee engine implementing the high water mark principle, onboarding supporting both direct and distributor paths with APMI registration checks, disclosure document delivery, and client reporting with an audit trail behind strategy and benchmark changes.
Performance or profit-sharing fees must be computed on the high water mark principle over the life of the investment — the highest value the portfolio previously reached — and charged only on gains above it. The charging frequency cannot be less than quarterly. It must survive contributions and withdrawals.
Among other things, a Mutual Fund-only PMS category with a ₹25 lakh minimum investment and ₹2 crore net worth, a fixed management fee capped at 2.5% of AUM, permission for foreign and 'to be listed' securities, and up to 10% of client AUM in investment grade unlisted debt under discretionary services. These are proposals, not law.
Yes. Under the current rules the first single lump-sum investment received from a client, whether as funds or securities, must not be less than ₹50 lakh. The ₹25 lakh figure appears in SEBI's consultation paper as a proposal for a new Mutual Fund-only category and has not been notified.
Buy when your strategies fit conventional mandates and your fee structures are ordinary — you are also buying compliance maintenance. Build when the mismatch is structural: unusual fee arrangements, a proprietary allocation process, multiple regulated entities, or a vendor roadmap that dictates when you can launch.
